For many households that own their home, it is the largest thing on the balance sheet. Whether it belongs in net worth sounds like a matter of taste but is settled by definition. What deserves thought is how you value the home, how you treat its loan and which second figure you keep beside the first. How to calculate your net worth works through the whole sum; this post takes the home on its own.
What home equity is
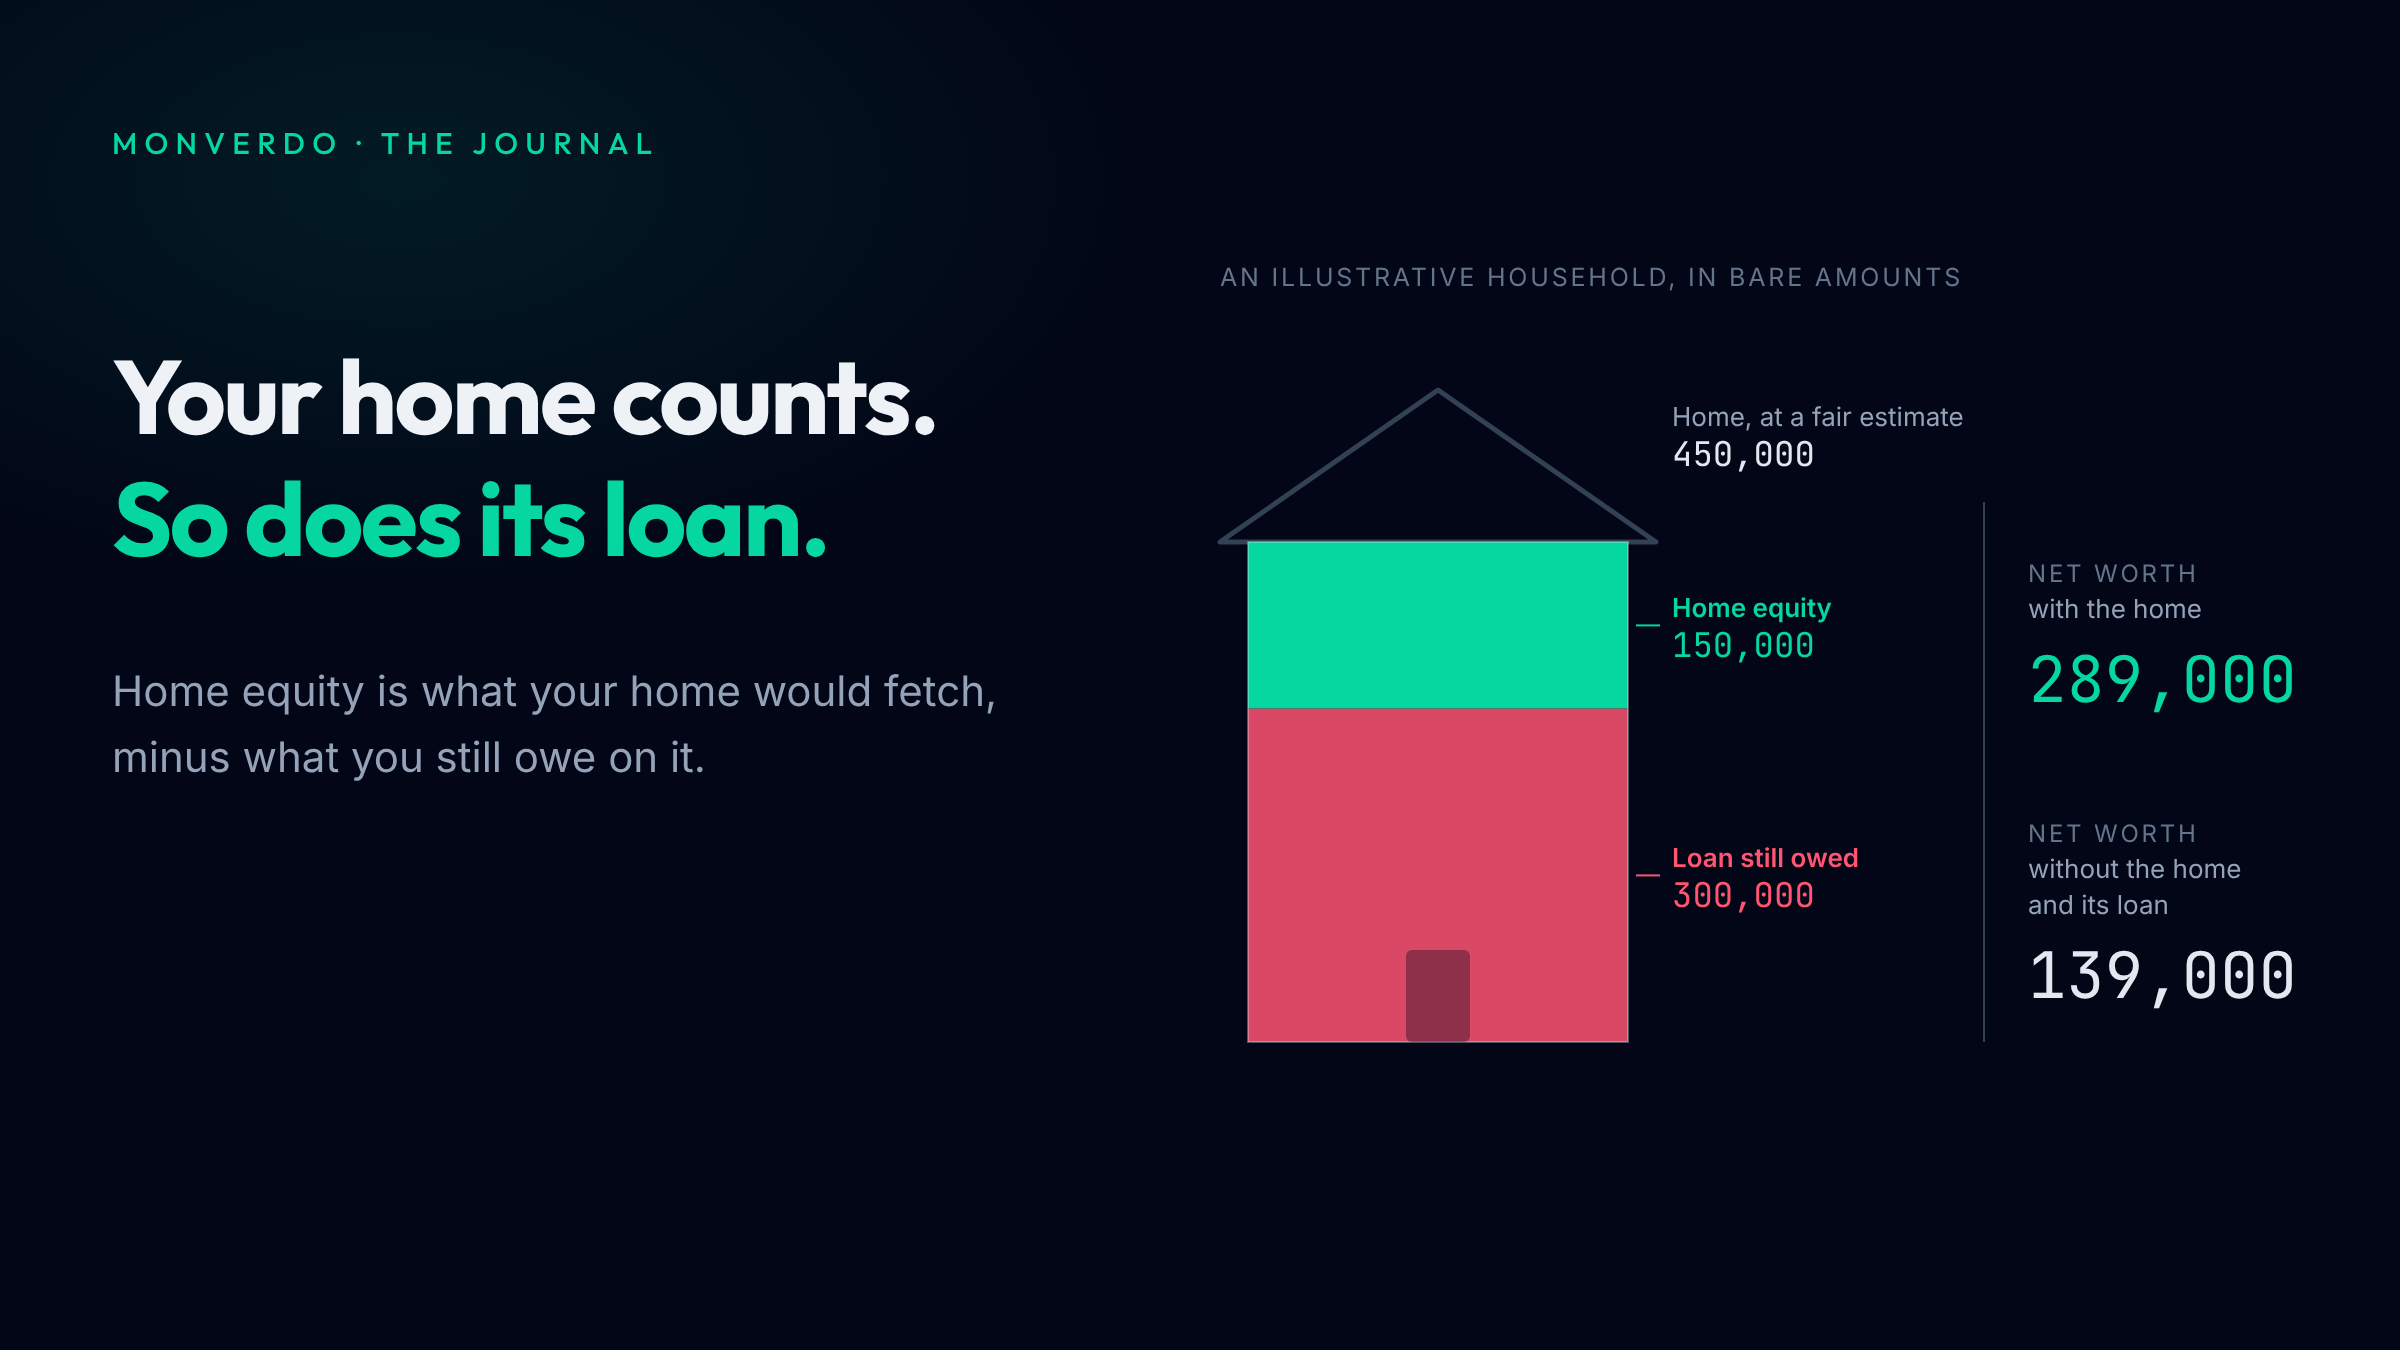
Home equity is what your home would fetch today minus what you still owe on every loan secured on it. A home estimated at 450,000 with 300,000 left on its loan holds 150,000 of equity. That 150,000 is the part of the home that is yours.
Equity grows in two ways: the price of the home rises, or the loan gets smaller. Only the first adds to your net worth. The part of a payment that comes off the loan moves value from your bank account into your home equity. Your bank balance falls, the loan falls by the same amount and the total stays where it was. The interest in each payment is different: it is a cost, and it lowers your net worth like any other. A year of steady repayments can lift your home equity a long way while the capital they repay adds nothing to what you're worth.
Why the home counts
Your home is yours. You could sell it, borrow against it or leave it to someone. Each of those turns its equity into something else of value. Official statistics count it: the OECD's measures of household wealth list the main home among a household's assets and the loans for buying it among its debts.[1]
Leave the home out and two very different households look the same. One has paid off its home and holds 50,000 in savings. The other rents and holds the same 50,000. Without the home they look equally well off. With it, the first owns a home the second does not. Net worth is the figure that shows the difference.
Why a second figure is worth keeping
You can't spend a bedroom. To reach your home equity you have to sell, which means buying or renting somewhere else, or borrow against it, which means paying interest. The equity is real but slow to reach. One securities regulator's rules leave out the main home, and the loan on it up to the home's value, when they test whether a person is wealthy enough for certain private investments.[2] That rule makes a good template for a second figure: take out the home and its loan, but keep any part of the loan the home no longer covers, because you would still owe that if you sold.
A home also concentrates risk. In the example below, a 10% fall in the home's price takes 30.0% off the equity, because the loan does not fall with it. Net worth drops 15.6%, while the figure without the home does not move. Watching both shows you how much of a year's change came from the home and its loan.
The sum, with the home and without it
| An illustrative household, in bare amounts | ||
| With the home | Without it | |
|---|---|---|
| What they own | ||
| Home, at a fair estimate | 450,000 | left out |
| Savings | 25,000 | 25,000 |
| Investments and pensions | 110,000 | 110,000 |
| Car | 15,000 | 15,000 |
| What they own | 600,000 | 150,000 |
| What they owe | ||
| Home loan balance | 300,000 | left out |
| Car finance | 9,000 | 9,000 |
| Card balances | 2,000 | 2,000 |
| What they owe | 311,000 | 11,000 |
| Own minus owe | ||
| Net worth | 289,000 | 139,000 |
Home equity is 450,000 minus 300,000, or 150,000: 51.9% of net worth. A 10% fall in the home's price (45,000) takes 30.0% off the equity and 15.6% off net worth; the figure without the home does not move. Bare amounts: the arithmetic is the same in any currency.
With the home, this household is worth 289,000. Without it and its loan, 139,000. More than half of what it is worth sits in the one asset it lives in.
Now suppose it pays an extra 10,000 off the loan from its savings. Net worth stays at 289,000. The figure without the home falls to 129,000, because 10,000 has moved from money the household can reach into a home it cannot. Neither figure is wrong. Read together, they show a choice the household made that each one alone would hide.
How to value your home
Use what the home would fetch if you sold it on the date, at a fair estimate. That is not what you paid for it, what an insurer would pay to rebuild it or what the house down the road is listed at. Recent sales of similar homes nearby are a good guide. A recent formal valuation is better still.
Two choices change the figure. Make each once and keep to it. The first is whether to take off what selling would cost, such as the agent's and legal fees. At an illustrative 4%, that takes 18,000 off the example's equity. Taking it off gives a figure closer to what you would bank; leaving it on keeps the figure in line with what a valuer would say the home is worth.
The second is how often to update. Updating often on a hunch makes the figure jump; once a year, or after something real changes, such as a renovation or a clear move in local prices, keeps it steady. Write the date beside the value. A rise in your estimate lifts your net worth, but it is not money in hand until you sell.
Five mistakes with the home
Counting the home but leaving out its loan. The loan is the other half of the equity, so the home without it overstates you by the whole balance.
Leaving the home out but keeping its loan. That understates you by the home's whole value, which is why a figure without the home takes both out.
Calling a repayment a rise in net worth. The part of each payment that reduces the loan moves money you already had. On the home itself, only a rise in its value adds to the total.
Forgetting other loans secured on the home. A second loan, or any other borrowing secured against the home, comes off its equity too.
Treating every property as the home. A flat you let out or a second home elsewhere is something you could sell without moving. It belongs in both figures.
Where a year's rise in your home equity comes from
Repayments can do more of the work than the price. In the demo household's last financial year, 74.5% of the rise in its home equity came from paying down the loan, one large extra payment included. The rest came from a rise in the home's value.
| A demo household's home and its loan, at the start and end of its financial year | |
| Start of the year | |
|---|---|
| Home, at the household's own estimate | £674,182 |
| Home loan still owed | £432,086 |
| Home equity | £242,096 |
| End of the year | |
| Home, at the household's own estimate | £691,711 |
| Home loan still owed | £380,957 |
| Home equity | £310,754 |
| What moved the equity | |
| Rise in the home's value | £17,529 |
| Loan repaid, including a £40,000 extra payment | £51,129 |
| Rise in home equity | £68,658 |
Of the £68,658, only the £17,529 rise in value added to the household's net worth; the £51,129 repaid moved value from its other accounts into its home equity. At the year end its home equity is 25.0% of its £1,243,934 net worth, which is £933,180 without the home and its loan. Whole pounds; the lines add to the totals shown.
The equity rose by far more than the home's value did. Net worth gained only the part the price added; the rest was money moving from one line of the balance sheet to another.
See what your home adds to what you're worth
A home value typed into a spreadsheet tends to stay there for years, with the loan balance beside it updated now and then. Monverdo is built to hold each property at a value you enter or a yearly rate you set, with a yearly reminder to check it. Beside it sits the equity left after every loan on it. Each repayment is split into the interest it cost and what came off the loan. Every amount is recorded twice, so the part of a repayment that comes off the loan shows as money leaving your bank and the loan falling by the same amount, never as a rise in what you're worth. Property and its loans sit in their own lines of your balance sheet, so on any date you pick, the figure without your home is one subtraction away. You know what your home adds to your net worth, and what you would have without it.
Further reading
A fictional demo household. Figures are for illustration, and product screens are concepts.
Monverdo measures and reports on your own figures. It does not give financial advice. Nothing on this site tells you what to buy, sell or do.
Sources
OECD, Wealth Distribution Database, "Main concepts", oecd.org (accessed 26 Oct 2026): net wealth is non-financial plus financial assets minus liabilities; the principal residence is a non-financial asset (NF1, "the residence where majority of household members live"); loans for constructing, purchasing or improving it are a liability (L1). The concepts follow the OECD Guidelines for Micro Statistics on Household Wealth (2013).
US Code of Federal Regulations, 17 CFR 230.501(a)(5)(i), the accredited investor net worth test, ecfr.gov (accessed 26 Oct 2026): the person's primary residence is not included as an asset; debt secured by it, up to its estimated fair market value, is not included as a liability; debt secured by it in excess of that value is.